Last Updated on October 30, 2026
Before you read: Whito Ltd is not authorised by the Financial Conduct Authority and holds no firm reference number. We do not arrange, advise on, recommend or sell any financial product, and we take no commission from any firm we write about. This page is general information, not financial, insurance or legal advice.
Plenty of new businesses run their first year through a personal current account. Every personal account we checked has a clause that says they should not.
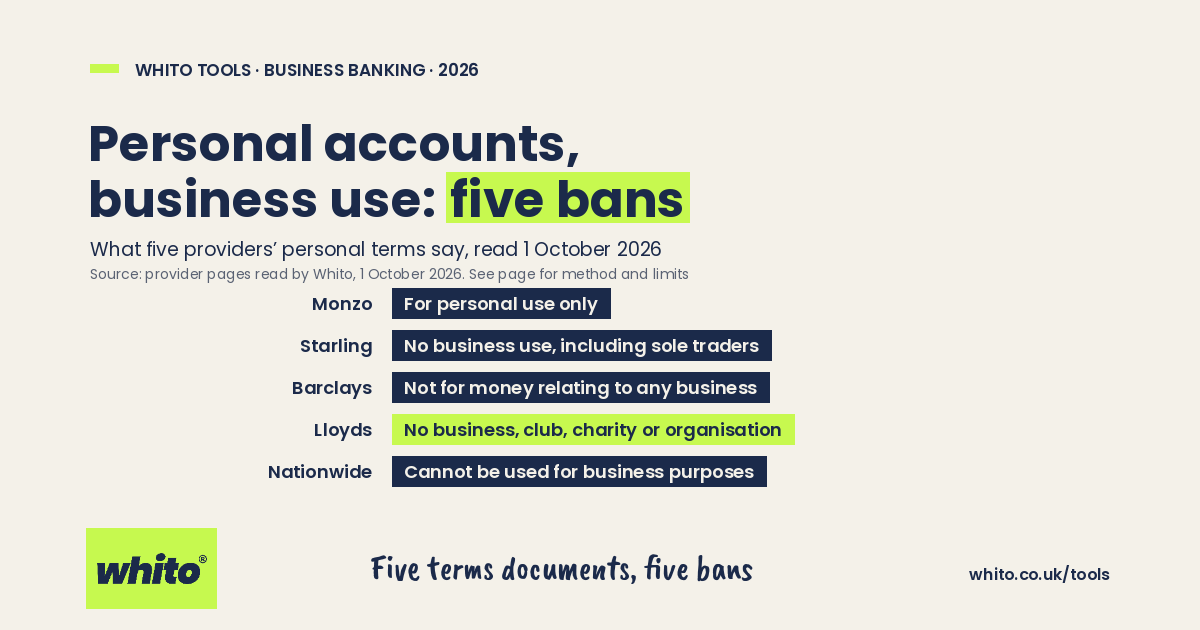
We read the personal current account terms of five UK current account providers on 1 October 2026. We read the personal account terms of five UK current account providers on 1 October 2026 and all five ban business use; Lloyds’s wording shuts out clubs and charities as well.
What the terms actually say
| Provider | The clause, from its personal terms |
|---|---|
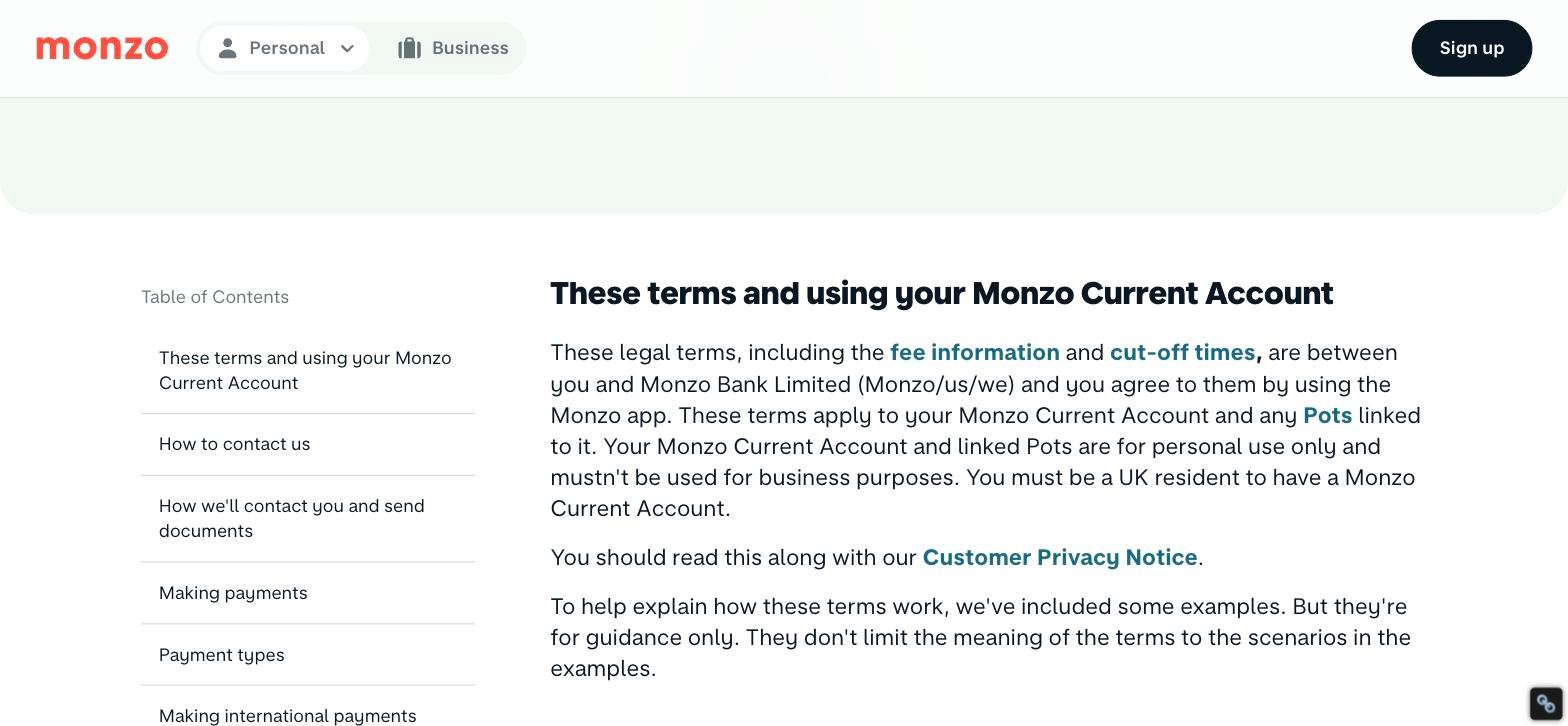
| Monzo | “Your Monzo Current Account and linked Pots are for personal use only and mustn’t be used for business purposes.” |
| Starling | “Only use this account for personal purposes. This means you can’t use it for any business purposes (including as a sole trader).” |
| Barclays | “The terms in this booklet cover only accounts for personal use. They’re not for money relating to any business you run.” |
| Lloyds | “Our accounts are for personal customers and must not be used by a business, club, charity or other organisation.” |
| Nationwide | “The account is for personal use and it cannot be used for business purposes.” |
Breaching the terms is the bank’s business as much as yours: the clause is what it points to if it reviews the account.
Limited companies have a harder rule
A company’s money is the company’s, and gov.uk’s guidance on company and accounting records says “your company’s banking must be separate from your personal banking” and that “The simplest way to keep your finances separate is to open a business bank account.” Paying company income into a director’s personal account muddles dividends, loans and salary, and your accountant will charge you to unmuddle it.
Sole traders: no law, two problems
No statute tells a sole trader to open a business account. The two practical problems are the terms above, which cover sole traders explicitly at some banks, and records: gov.uk says you must keep records of your business income and expenses for your Self Assessment tax return if you are a sole trader or partner. A separate account turns that record into a bank statement.
The cost argument has gone
The reason people risk it is price, and the price is now zero at several providers. Six accounts cost our model online sole trader nothing at all in a standard year; our free business bank accounts page lists them, and best business bank accounts UK prices the full set. If cash or clients push you toward a particular provider, the trade pages linked from it go deeper.
Open the business account before the bank reads your statements for you. It costs nothing at several providers, and it makes January’s Self Assessment an export instead of an archaeology dig.
Questions
Is it illegal to use a personal account for business?
For a limited company the money belongs to the company, and gov.uk says the company’s banking must be separate from your personal banking. For a sole trader no law names a bank account. Every personal account we checked bans business use in its terms.
Can a sole trader use a personal bank account?
HMRC requires records of business income and expenses for Self Assessment, and a mixed account makes those records harder. The bigger problem is the account terms: Starling’s personal terms say you cannot use the account for any business purposes, including as a sole trader.
What happens if I run a business through my personal account?
You are outside the account’s terms, which the bank can act on. Lloyds’s personal terms say the accounts must not be used by a business, club, charity or other organisation. Free business accounts exist, so the saving is smaller than it looks.
Method, limits and legal position
This page is general information for UK businesses. It is not financial, insurance or legal advice, and it does not take account of your circumstances. Fees, rates, terms and eligibility change, so check the provider’s own current terms, and take regulated advice where you need it, before you act.
Whito Ltd is not authorised by the FCA, holds no firm reference number and cannot approve financial promotions under section 21 of the Financial Services and Markets Act 2000. Nothing on this page is an invitation or inducement to take out any financial product, and nobody pays to appear on Whito.
Where this page describes a firm’s published prices, terms or register entry, that is a dated record of what the firm or the register showed, not a verdict on the firm. A firm being on the FCA register does not prove that the person contacting you works for it: clone firms copy real firms’ details. Contact a firm using the details listed on the register, and if they do not match, call the FCA on 0800 111 6768.