Last Updated on October 30, 2026
Before you read: Whito Ltd is not authorised by the Financial Conduct Authority and holds no firm reference number. We do not arrange, advise on, recommend or sell any financial product, and we take no commission from any firm we write about. This page is general information, not financial, insurance or legal advice.
Most business owners assume every account with a sort code is a bank account. Some are not, and the difference decides what happens to your money if the provider fails.
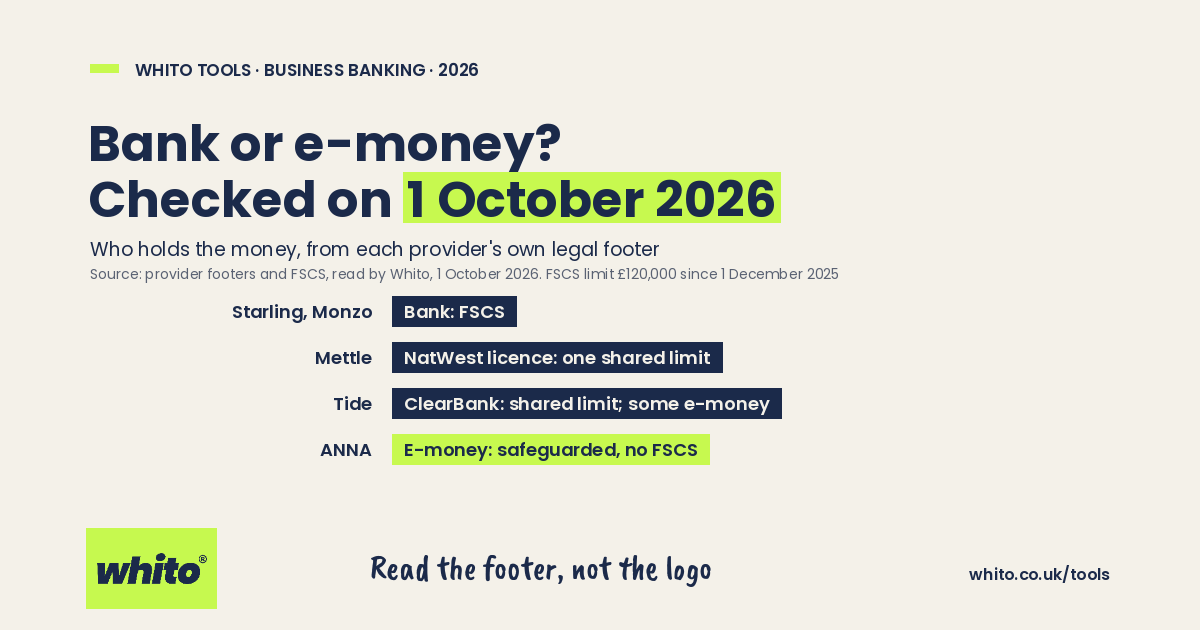
We read the legal footers and protection pages of 18 UK business account providers on 1 October 2026. Two of the providers we priced, Tide and Countingup, said some of their customers hold e-money accounts with sort code 23-69-72. Those accounts are safeguarded, and the FSCS does not cover them. Mettle’s footer names an e-money account too.
In short
Bank accounts are covered by the Financial Services Compensation Scheme up to £120,000 per eligible depositor per bank. The Bank of England confirmed the rise from £85,000 from 1 December 2025.
E-money accounts are not. The FCA says funds held by payments and e-money firms are not directly protected by the FSCS. The firm must keep your money separate from its own, which is called safeguarding.
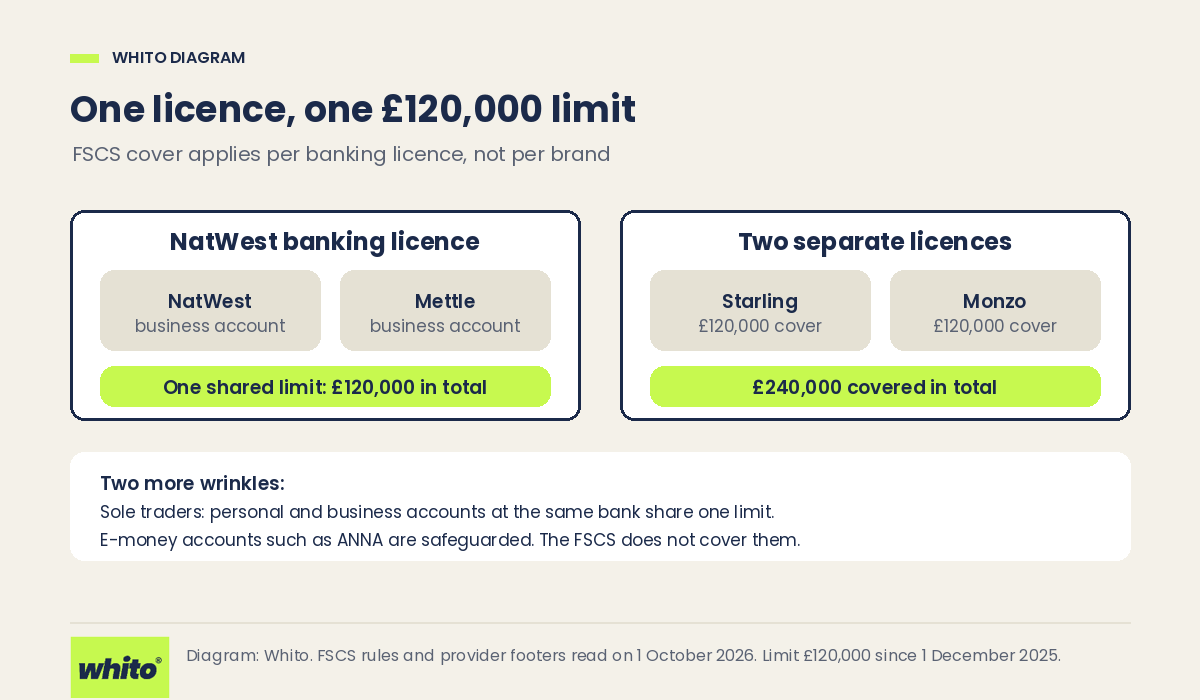
Brands that share a banking licence share one limit. The FSCS says protection applies at firm level and may be shared across brands under the same authorisation.
Who is behind each account
| Account | Who holds your money | FSCS |
|---|---|---|
| Starling | Starling Bank (licensed bank) | Yes, up to £120,000 |
| Monzo Business | Monzo Bank Limited | Yes |
| Mettle | National Westminster Bank plc trading as Mettle; Mettle also names an e-money account provided by PPS (Prepay Technologies) | Bank account: yes, shared with NatWest. E-money account: no |
| Tide | ClearBank Ltd for current and savings accounts | Yes, shared across all accounts with ClearBank. E-money accounts (sort code 23-69-72): no |
| Countingup | Griffin Bank (sort code 04-36-15) | Yes. E-money accounts opened before 3 August 2026 (sort code 23-69-72): no |
| Revolut Business | Revolut Ltd (e-money) until moved to Revolut Bank UK Ltd | Only once moved |
| ANNA | PayrNet Limited, an e-money institution | No on the main account; safeguarded |
| Virgin Money | Nationwide Building Society trading as Virgin Money | Yes, shared with Nationwide |
| Zempler Bank (formerly Cashplus) | Zempler Bank Limited | Yes |
| Barclays, HSBC UK, Lloyds, NatWest, Santander, Co-operative Bank, Metro Bank, TSB, Allica Bank | Each bank in its own name | Yes |
Three cases where the limit is smaller than you think
Two brands, one bank
Money at NatWest and Mettle counts towards one £120,000. So does money at Nationwide and Virgin Money. Tide’s cover is shared with every other account you hold at ClearBank.
Sole traders count as one person
The FSCS treats a sole trader as an individual, so personal and business accounts at the same bank share one limit. A limited company is a separate depositor from its directors.
A sort code that tells you
If your Tide or Countingup sort code is 23-69-72, your account is e-money. Countingup says accounts on that sort code were opened before 3 August 2026. Tide’s current accounts sit with ClearBank. Ask your provider whether you can move to the bank account, and what happens to your account number and Direct Debits.
What to do with this
- Find the legal footer of your provider’s website and read who provides the account.
- Check your sort code against the table above.
- If you hold more than £120,000, split it across banks with different licences. Two brands on one licence share a single limit.
- Keep tax money in a separate account. Several providers offer pots or savings accounts for this; check those are covered too.
Protection is one test. Fees are the other: our best business bank accounts UK page prices a year at each.
Read the footer. The company named there is the one holding your money.
Questions
How much of my business money does the FSCS protect?
Up to £120,000 per eligible depositor per bank, building society or credit union. The limit rose from £85,000 on 1 December 2025. Limited companies and LLPs are eligible depositors.
Is Tide FSCS protected?
Tide current and savings accounts are provided by ClearBank and eligible deposits are protected up to £120,000, shared across all accounts with ClearBank. Tide says some members hold e-money accounts with sort code 23-69-72, which are safeguarded rather than FSCS protected.
Is ANNA a bank?
No. ANNA’s main business account is e-money provided by PayrNet, which is safeguarded under the Electronic Money Regulations 2011. ANNA says FSCS protection applies only to its separate savings account.
Does Mettle share an FSCS limit with NatWest?
Yes. Mettle accounts are provided by National Westminster Bank plc trading as Mettle, and the FSCS applies its limit per authorised firm. Money at NatWest and Mettle counts towards one £120,000.
Is Revolut Business covered by the FSCS?
Once your account has moved to Revolut Bank UK, eligible deposits are covered up to £120,000. Until then it is an e-money account with Revolut Ltd. Revolut had not published the date for each customer when we read its pages.
Method, limits and legal position
This page is general information for UK businesses. It is not financial, insurance or legal advice, and it does not take account of your circumstances. Fees, rates, terms and eligibility change, so check the provider’s own current terms, and take regulated advice where you need it, before you act.
Whito Ltd is not authorised by the FCA, holds no firm reference number and cannot approve financial promotions under section 21 of the Financial Services and Markets Act 2000. Nothing on this page is an invitation or inducement to take out any financial product, and nobody pays to appear on Whito.
Where this page describes a firm’s published prices, terms or register entry, that is a dated record of what the firm or the register showed, not a verdict on the firm. A firm being on the FCA register does not prove that the person contacting you works for it: clone firms copy real firms’ details. Contact a firm using the details listed on the register, and if they do not match, call the FCA on 0800 111 6768.