Last Updated on October 1, 2026
A law firm needs two kinds of account, and the regulator decides where one of them can be. Start with the client account, then choose the office account around it.
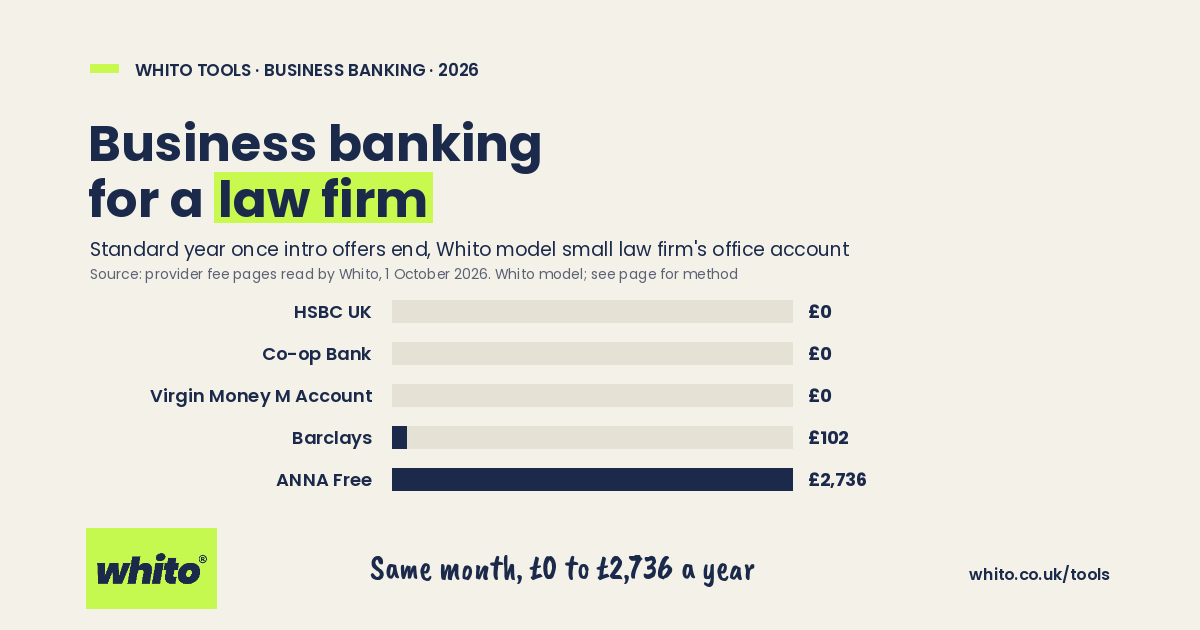
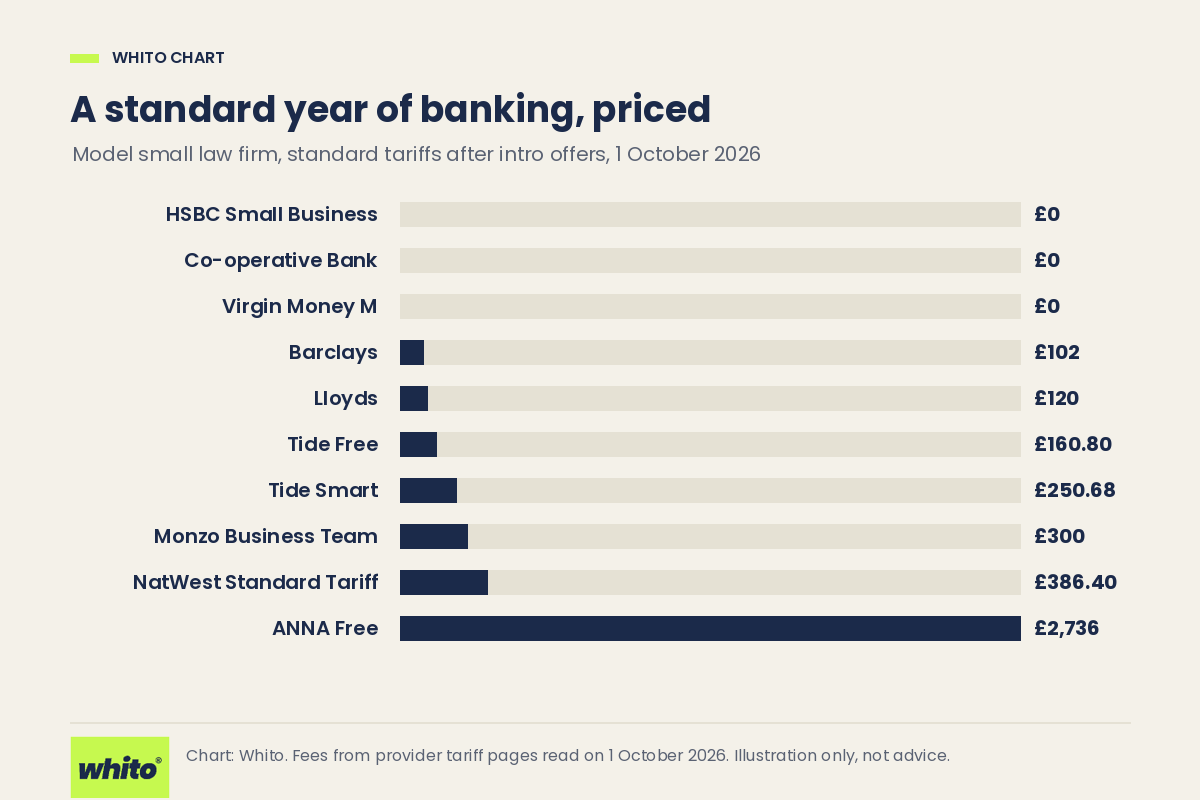
We priced a standard year at 15 UK business accounts on 1 October 2026 for a small firm’s office account, then checked which providers take firms that hold client money. For our model small law firm’s office account, a standard year of banking cost £0 at 3 of the accounts we priced, including HSBC UK Small Business Banking and Co-operative Bank Business Bank Account, and £2,736 at ANNA Free.
The accounts that suit law firms
- HSBC UK Small Business Banking, £0 a year. No monthly fee on the office account, and HSBC UK describes a Clients Deposit Account for legal professionals.
- Co-operative Bank Business Bank Account, £0 a year. No monthly fee and free electronic payments, with a branch bank behind it.
- Virgin Money M Account, £0 a year. No monthly fee, free electronic payments and a branch. For turnover under £1m.
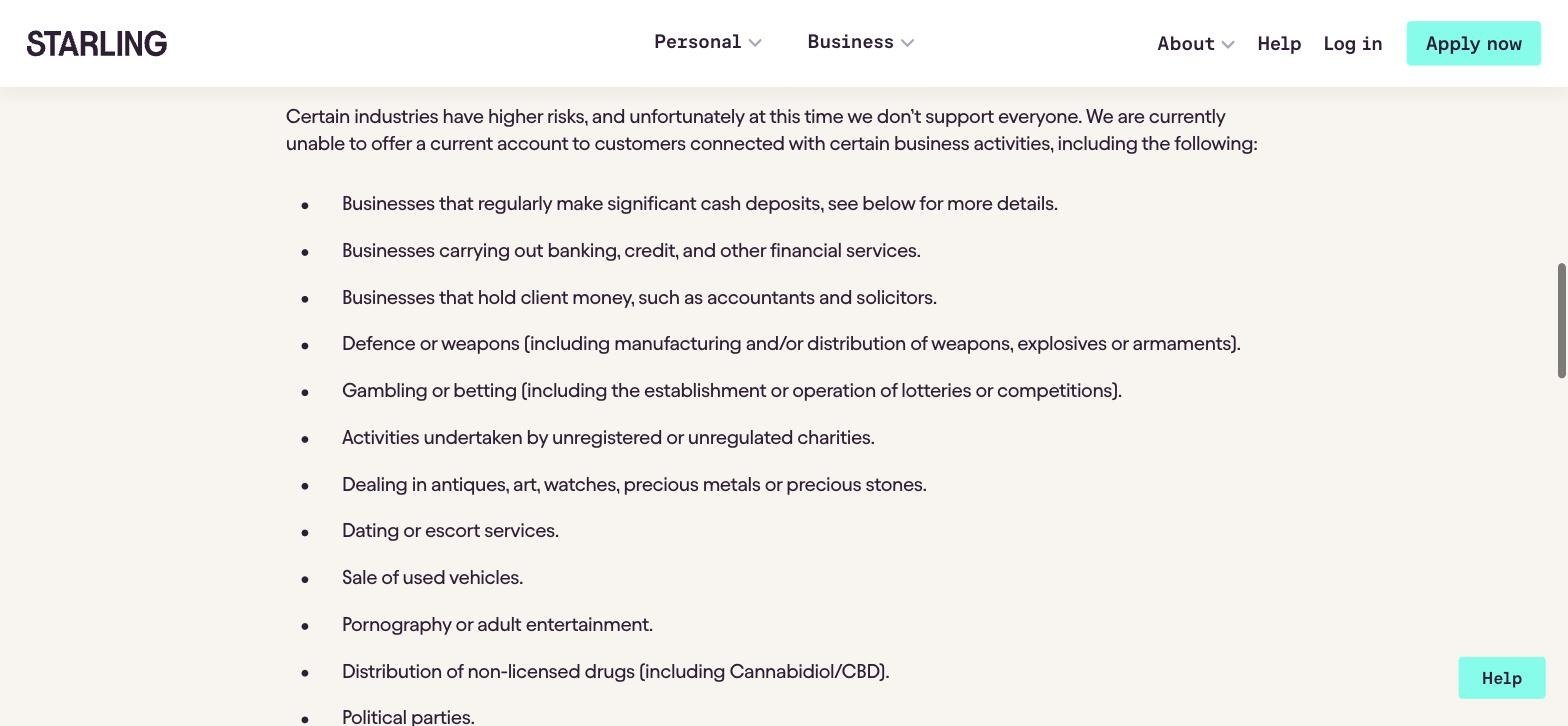
Starling does not take businesses that hold client money, and Monzo also lists probate and estate management among the industries it does not support. The left-out table below has the rest.
The model month
| Each month | Small law firm, office account (limited company) |
|---|---|
| Payments received | 30 (£25,000 in total) |
| Transfers sent | 30 (including 8 staff payments) |
| Direct Debits | 12 |
| Debit card purchases | 20 |
| Cash paid in | None |
What a standard year cost a small law firm
| Account | Standard year | What drives the bill |
|---|---|---|
| HSBC UK Small Business Banking | £0 | Post Office cash 1.5% (tariff from 14 December 2026) |
| Co-operative Bank Business Bank Account | £0 | Cash £1.50 per £100 |
| Virgin Money M Account | £0 | Cash 90p per £100; turnover under £1m |
| Barclays Business Current Account | £102 | £8.50 a month after 12 free months; cash 60p per £100 |
| Lloyds Business Account | £120 | £10 a month after 12 free months; counter cash £1.60 per £100 |
| Tide Free | £160.80 | 20p per transfer in or out after 5 a month |
| Tide Smart | £250.68 | £12.49 a month, 30 transfers included |
| Monzo Business Team | £300 | £25 a month Team plan (staff access, bulk payments) plus £1 per cash deposit |
| NatWest Standard Tariff | £386.40 | 35p per electronic item and card payment; cash 95p per £100 plus 95p a deposit |
| ANNA Free | £2,736 | E-money; 0.95% of money received above £1,000 a month |
Left out for this trade, and why:
| Account | Why it is not in the table |
|---|---|
| Starling with Bulk Payments | Does not take businesses that hold client money |
| Mettle (NatWest) | Only one owner can access the account |
| Santander Business Classic | Maximum two directors, owners or partners |
| Revolut Business Basic | Says a Business account cannot hold or manage client funds |
| Countingup | We found no team access or bulk payments on its pages |
What matters for law firms beyond the fee
Where client money must sit
SRA Accounts Rule 3.1: “You only maintain a client account at a branch (or the head office) of a bank or a building society in England and Wales.” Barclays (Clients Premium Account), HSBC UK (Clients Deposit Account), Lloyds (designated and pooled client accounts through its corporate bank), NatWest (Clients’ Monies Service for firms with 25 or more client accounts or £300,000 in balances, otherwise Client Deposit Manager), Metro Bank (Client Premium Deposit Account) and Allica Bank (pooled and designated client deposit accounts) all describe client account products on their own sites.
Who will not take it
Starling lists “businesses that hold client money, such as accountants and solicitors” among the industries it does not support. Monzo says it does not allow Monzo Business to be used as a client trust account, and Revolut says a Business account cannot be used to process money from clients.
Office and client at one bank
Holding both at one bank keeps reconciliation and transfers between them simple. Splitting them can save on the office account, but check the client account provider does not require it.
Before you open
- Choose the client account provider first.
- Check how payments between client and office account are approved and recorded.
- Price your own month: count a month of payments in, payments out, Direct Debits and cash, then use the fees on our best business bank accounts UK page.
- Check protection: who holds the money and whether it shares an FSCS limit. See FSCS protection on business accounts.
More for law firms: the solicitor hub and solicitor software and tools. Every trade we priced: business banking by trade.
For a law firm, the cheapest office account is only cheap if it sits comfortably beside your client account.
Questions
What is the best business bank account for law firms?
In our model of a small law firm, priced from published fees on 1 October 2026, 3 accounts tied for the cheapest standard year at £0, including HSBC UK Small Business Banking, Co-operative Bank Business Bank Account and Virgin Money M Account. The cheapest high street bank was HSBC UK Small Business Banking at £0. Your own mix of payments and cash decides the answer.
Where must a solicitor hold client money?
Under SRA Accounts Rule 3.1, a client account must be held at a branch or the head office of a bank or building society in England and Wales.
Can a law firm bank with Starling or Monzo?
Starling lists businesses that hold client money, such as solicitors, among those it does not support. Monzo says Business accounts cannot be used as client trust accounts, and lists probate and estate management among the industries it does not support, so a firm would need a separate client account elsewhere.